
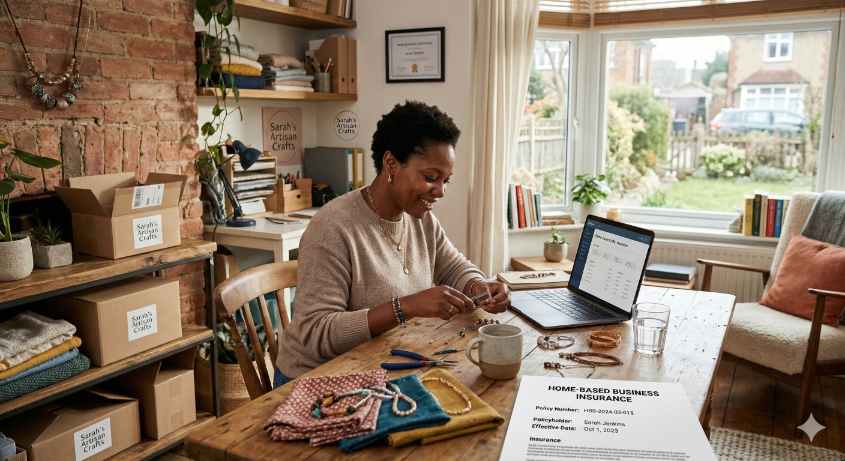
Most standard homeowners insurance policies do not cover home-based businesses, as they specifically exclude “business pursuits” from liability and property protection. While a personal policy protects your furniture and clothing, it often limits business equipment coverage to $2,500 and provides zero liability protection for customer injuries or product-related lawsuits. To be fully protected, entrepreneurs need a home business endorsement or a standalone commercial policy.
Bridging the Business Insurance Gap
Operating a business from home without specific commercial coverage leaves your equipment and personal assets vulnerable to total loss.
- Property Limits: Homeowners policies have very low caps on business-related gear and inventory.
- Liability Exclusion: Standard personal insurance typically denies claims for business-related slip-and-falls.
- Product Risk: Personal liability does not cover injuries caused by products you sell or manufacture.
- Strategic Solutions: Options include policy endorsements, in-home business policies, or a full Business Owners Policy (BOP).
Table of Contents
- The Property Gap: Inventory and Equipment
- The Liability Trap: Customers and Deliveries
- Solutions for Home-Based Business Owners
- Why Local Business Insurance Matters
- FAQ: Home-Based Business Insurance in South Dakota
The Property Gap: Inventory and Equipment
A common misconception among Sioux Falls entrepreneurs is that “if it’s in my house, it’s covered.” However, homeowners insurance is designed for personal effects, not commercial assets.
Definition: Business Personal Property (BPP)
The furniture, fixtures, equipment, and inventory owned by a business and used in its operations. In a home-based setting, BPP requires specific coverage because personal policies usually cap these items at a small fraction of their actual value.
Common Items at Risk
- Specialized Gear: High-end cameras for photographers or specialized tools for makers.
- Inventory: Stock kept on-hand for shipping to customers through platforms like Etsy.
- Office Equipment: Dedicated computers, printers, and servers used exclusively for work.
The Liability Trap: Customers and Deliveries
Liability is the largest financial risk for home-based business owners. Your homeowners policy is intended to cover “social guests.” The moment a visitor enters your home for a business transaction—such as a music lesson, a consultation, or picking up a package—the personal liability coverage typically ceases to apply.
| Risk Scenario | Homeowners Policy Coverage | Commercial Policy Coverage |
| Social Guest Slip-and-Fall | Covered | Covered |
| Client/Customer Slip-and-Fall | Typically Excluded | Covered |
| Product-Related Injury | Excluded | Covered (Product Liability) |
| Airbnb/Rental Injury | Excluded (Commercial Use) | Covered (Specialized Rental) |
Solutions for Home-Based Business Owners
Protecting your livelihood is often more affordable than many business owners expect. At Bechtel Insurance, we sit down with you to determine which of these three paths fits your current scale:
- Home Business Endorsement: An add-on to your existing home policy for very small, low-risk operations. It increases equipment limits and adds limited liability.
- In-Home Business Policy: A standalone plan providing more robust protection for inventory and a wider range of liability risks than a simple endorsement.
- Business Owners Policy (BOP): The comprehensive choice for growing businesses. A BOP combines property, liability, and business interruption insurance into one cost-effective package.
Why Local Business Insurance Matters
Since 1972, Bechtel Insurance has helped Sioux Falls families protect their legacies. Because we are an independent, second-generation agency, we understand that your home-based business is more than a “side hustle”—it is your livelihood and your future. Dave and Heather can help you navigate the transition from personal to commercial coverage as your business grows.
FAQ: Home-Based Business Insurance in South Dakota
Does my homeowners insurance cover my Etsy business?
Generally, no. While it may cover a small amount of equipment, it likely excludes your inventory and any liability if a product you sell causes an injury. A home business endorsement is usually required.
What if I host guests through Airbnb in Sioux Falls?
Standard homeowners policies often exclude coverage for short-term rentals because the home is being used as a “hotel.” You need specialized host protection or a commercial endorsement to ensure you are covered for guest injuries.
Is a home-based business policy expensive?
For many small home-based businesses, basic coverage can cost as little as $150 to $300 per year. This is a small price to pay compared to the cost of a denied lawsuit or a total loss of equipment.
Do I need Workers’ Compensation for my home business?
If you have employees—even part-time—South Dakota law and general safety best practices suggest Workers’ Comp. While not always mandated for the smallest businesses, it protects your bottom line from injury claims.
Will my homeowners policy cover my business laptop if it’s stolen from my car?
Most homeowners policies have very strict (and low) limits for business property away from the premises. A commercial policy provides broader protection for mobile equipment like laptops and cameras.
Can I deduct business insurance premiums on my taxes?
In many cases, yes. Since the insurance is a necessary cost of doing business, the premiums are typically tax-deductible. Consult with a tax professional regarding your specific situation in South Dakota.
Your entrepreneurial spirit deserves absolute protection against lawsuits and property damage. At Bechtel Insurance, we pride ourselves on the personal touch, helping you understand how to put the industry’s best products to work for your unique needs. Don’t wait for a claim to discover a gap in your coverage—let’s secure your business today.
By: Bechtel Insurance Team
Last Updated: March 4, 2026
Credentials: Bechtel Insurance is an independent, family-owned agency serving the Sioux Falls, SD area since 1972, specializing in personalized family and business insurance planning.